Corporate wellness programs are often pitched to business owners as a "nice to have" something that improves morale, helps with recruitment, and signals that a business cares about its people. All of that is true. What's less widely understood is that a genuinely well-run wellness program can also have a measurable effect on some of the insurance costs a business carries every year, particularly workers' compensation and, in some cases, group health-related benefits.
The Connection Between Wellness and Claims
Workers' compensation premiums are shaped significantly by claims history. A workforce that experiences fewer musculoskeletal injuries, fewer stress-related absences, and faster returns to work after an incident will, over time, be rated more favourably than one with a consistent pattern of claims regardless of how good the underlying safety equipment or procedures are on paper.
Wellness programs influence this indirectly but meaningfully. A physically healthier workforce tends to recover faster from minor strains. A workforce with better mental health support tends to have fewer prolonged stress-related absences. None of this shows up as a direct, immediate premium discount but it shows up over time, in the same way that a safer workplace culture gradually improves an experience rating.
What "Wellness Program" Actually Means in Practice
The term covers a wide range of initiatives, and not all of them carry equal weight. At the more effective end:
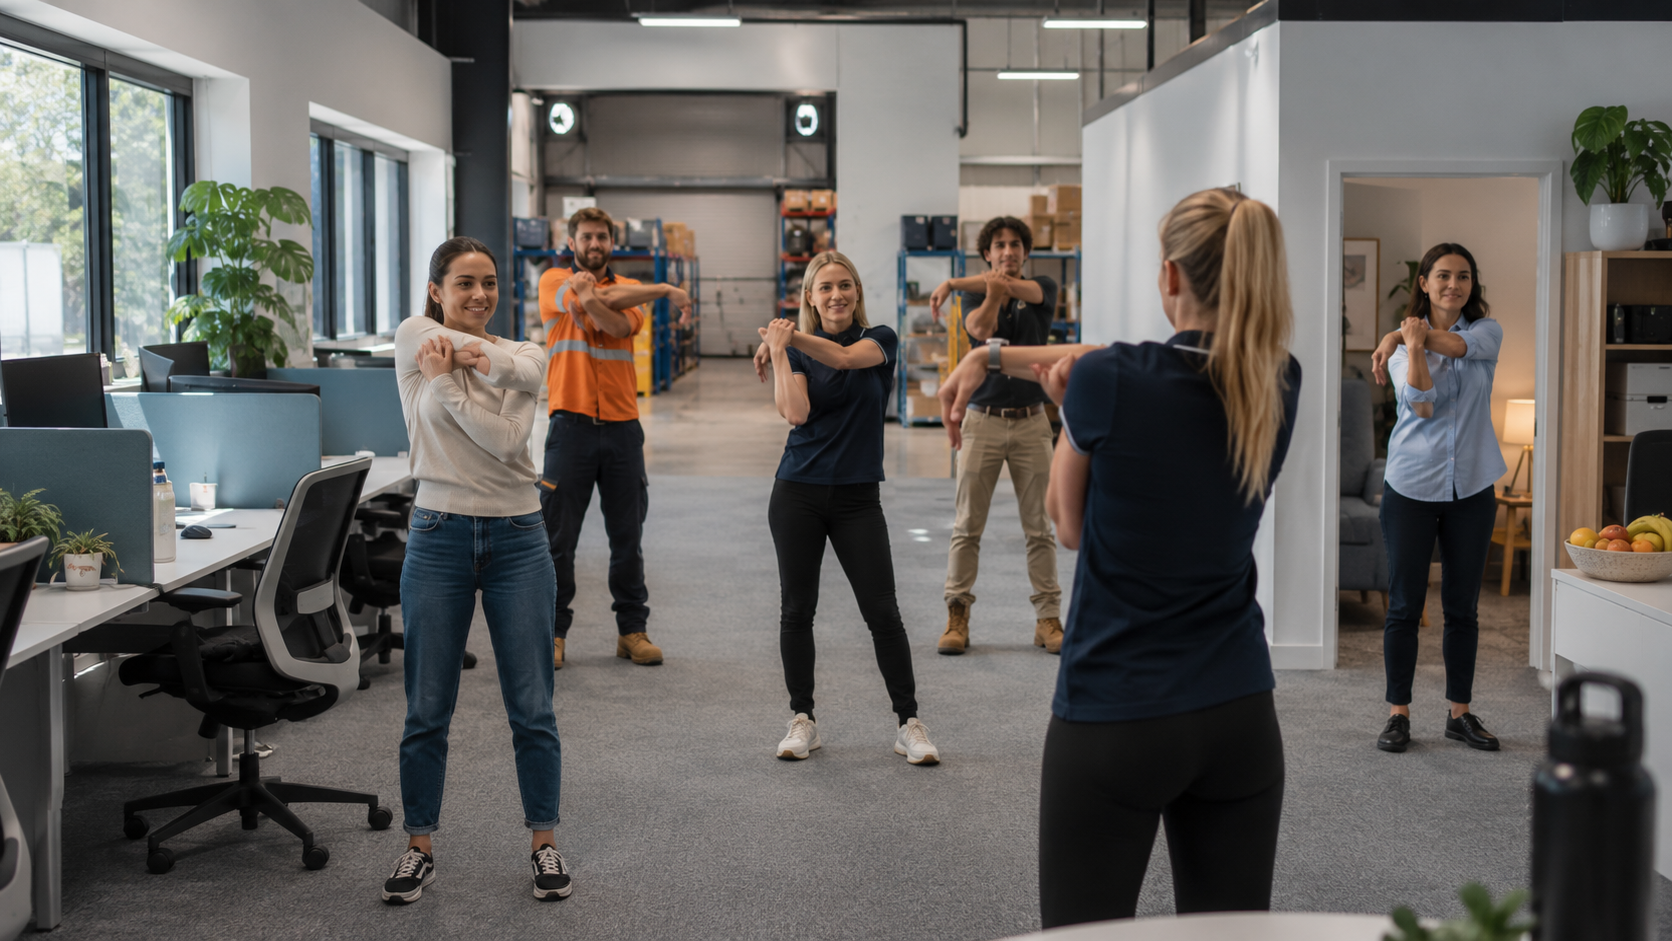
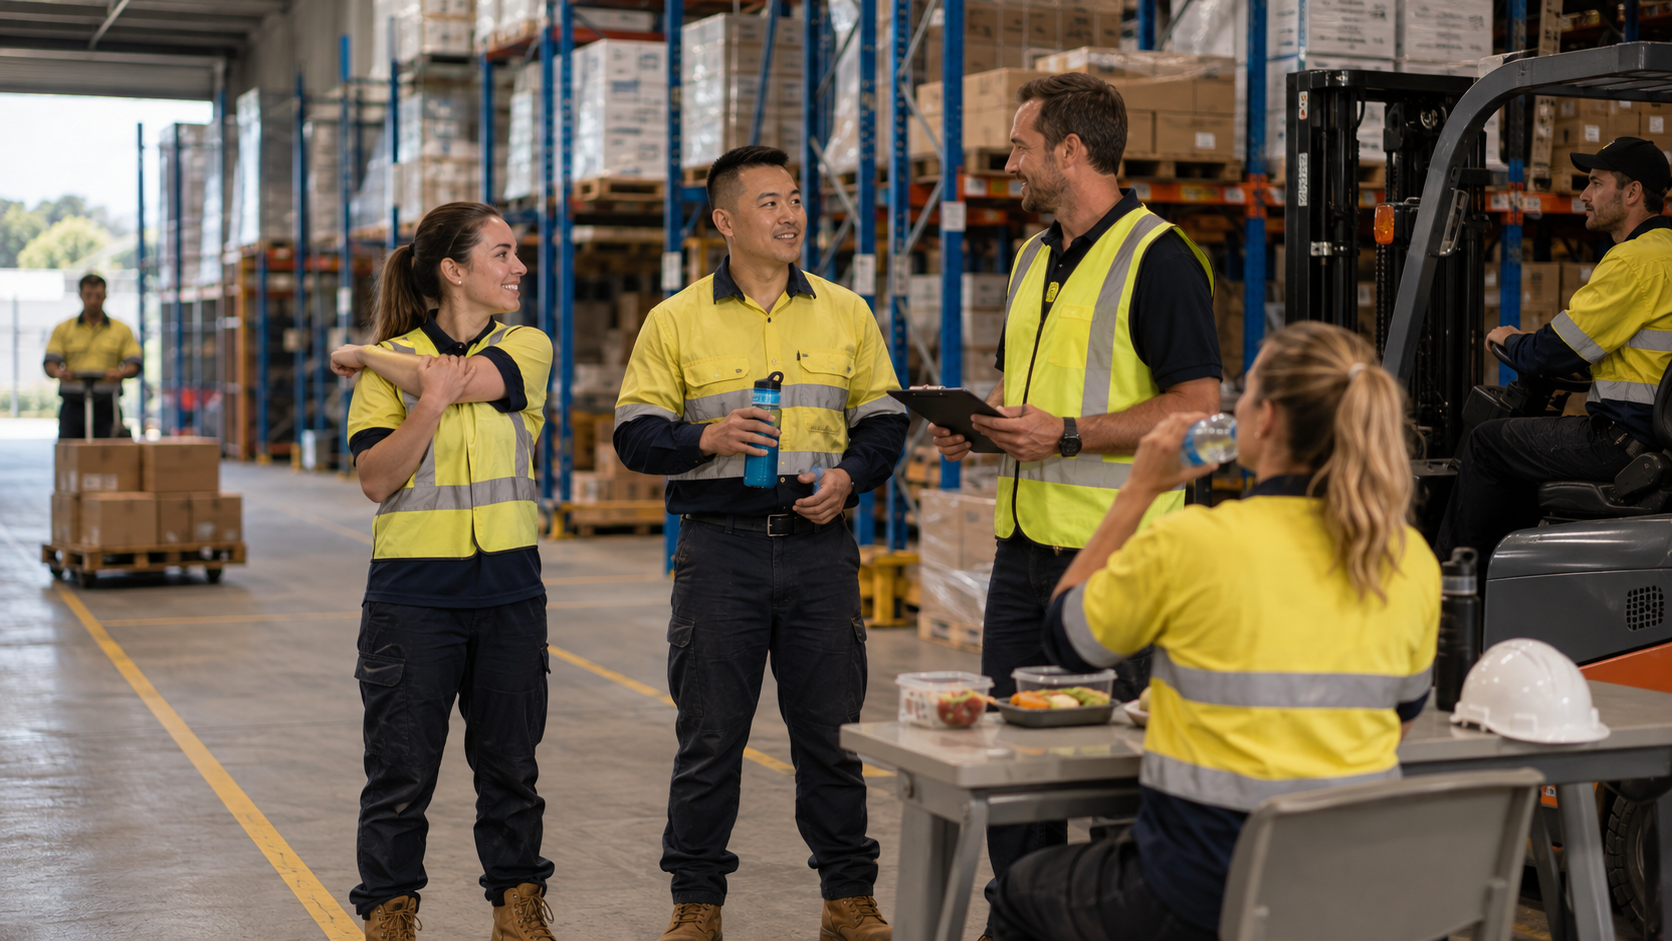
- Structured movement or stretching breaks for physically repetitive roles
- Subsidised gym memberships or on-site fitness sessions
- Access to an Employee Assistance Program (EAP) for confidential mental health support
- Flu vaccination programs and basic preventative health checks
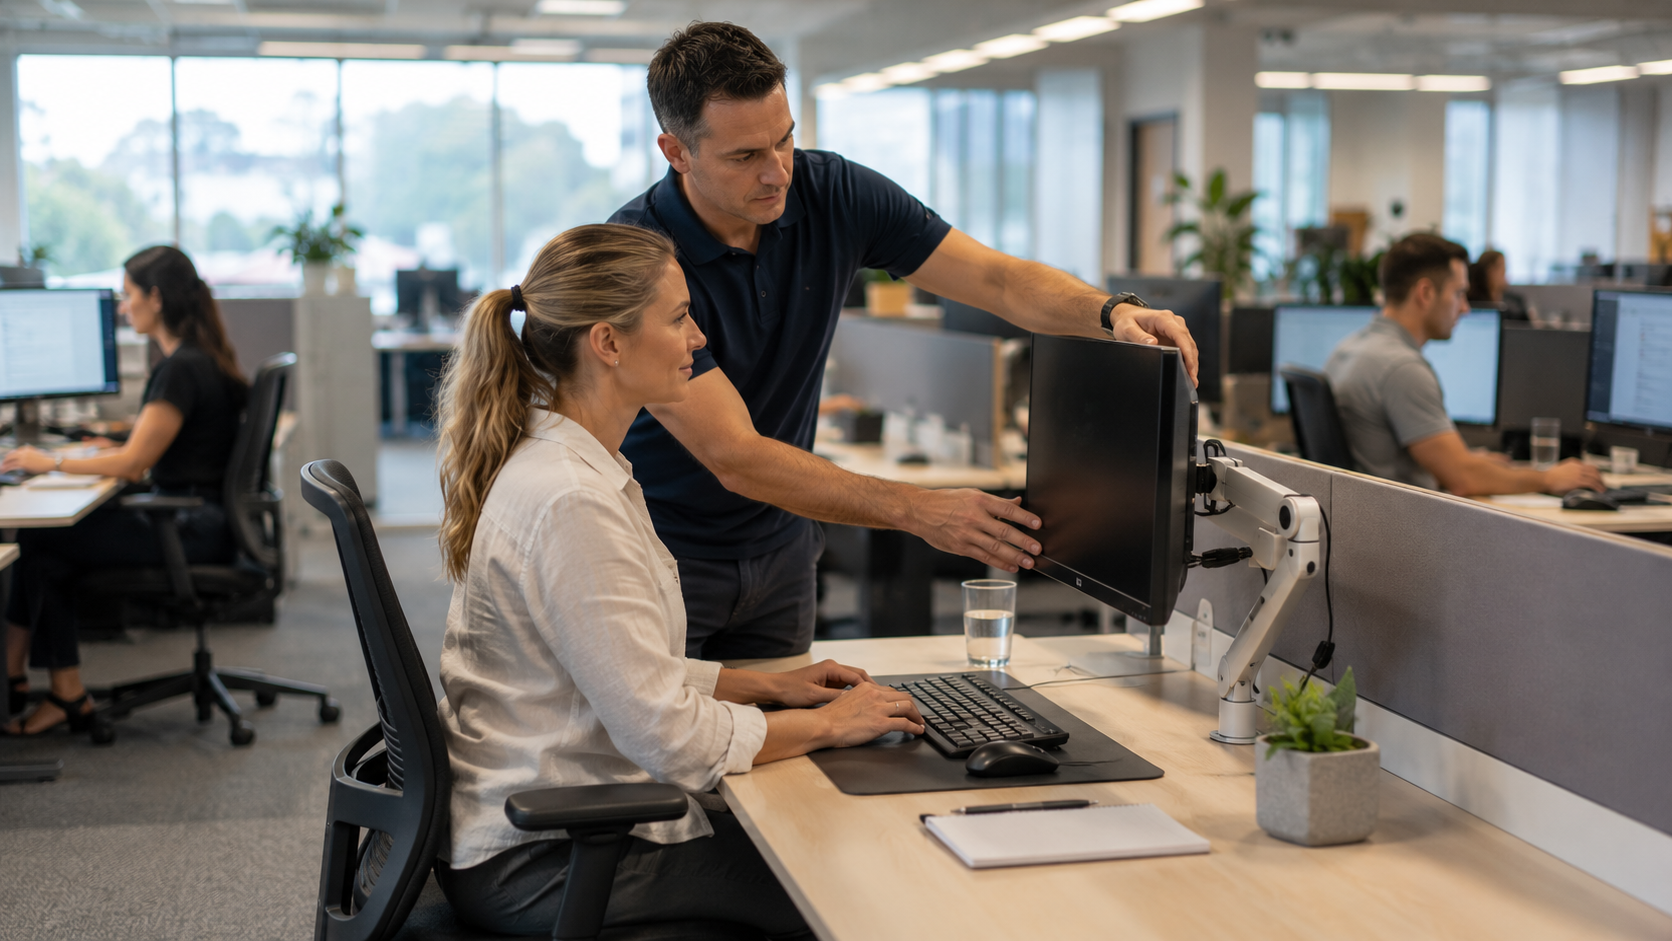
- Ergonomic assessments for desk-based staff
At the less effective end initiatives that generate goodwill but rarely move the needle on claims are one-off wellness days or generic posters, without any sustained follow-through. The distinction matters: a wellness program that exists as an annual event photographed for social media is unlikely to meaningfully change claims patterns. One that's built into ongoing operations is far more likely to.
The Mental Health Dimension
A significant and growing proportion of workers' compensation claims in Australia now relate to psychological injury rather than physical injury often linked to workload, workplace conflict, or sustained stress. This is an area where wellness initiatives can have an outsized impact, because psychological injury claims tend to involve longer recovery periods and higher costs than many physical injury claims.
Providing genuine, accessible mental health support not just an EAP phone number buried in an onboarding pack, but a workplace where staff feel able to raise concerns before they escalate is increasingly one of the more direct ways wellness investment intersects with claims cost.
What Doesn't Automatically Follow
It's worth being realistic about what a wellness program will and won't do. Having a gym membership subsidy in place does not automatically reduce your premium the way installing safety guards on machinery might. Insurers assess risk based on demonstrated claims history and workplace practices, not on the existence of a wellness perk in isolation. The connection between wellness investment and lower costs is real, but it plays out over time, through fewer and less severe claims not as an immediate line-item discount for having a program on paper.
Building a Program That Actually Moves the Needle
The most effective wellness programs share a few common features: they're specific to the actual physical and mental demands of the roles involved, rather than generic; they're genuinely accessible rather than technically available but rarely used; and they're sustained over time rather than treated as a single initiative to point to.
A manufacturing business with high manual handling demands benefits more from targeted stretching and movement breaks than from a generic wellness newsletter. An office-based professional services firm may get more value from mental health support and ergonomic assessments than from a subsidised gym membership few staff actually use.
Where to Start
For businesses without an existing program, a reasonable starting point is understanding where your current claims are actually coming from physical strain, stress-related absence, or a mix and building initiatives that respond directly to that pattern, rather than adopting a generic package because it's popular elsewhere.
Curious how workplace wellness initiatives might affect your insurance arrangement over time? Connect with a UIG Authorised Representative to talk through your specific workforce.
A Realistic Example
Two similarly-sized warehousing businesses both carry workers' compensation cover. One introduces structured five-minute stretching breaks before each shift, alongside a genuinely promoted EAP that staff are actively encouraged to use, not just told about once during induction. The other maintains the status quo. Over three years, the first business sees a modest but real decline in manual handling claims and a faster average return-to-work time following the claims that do occur. None of this happened overnight, and no single claim was obviously prevented by the stretching program but the cumulative pattern, assessed over time, is different enough to show up in the business's experience rating.
Questions Worth Asking About Your Own Workplace
- Do we actually know where our claims are coming from physical strain, stress-related absence, or a mix of both?
- Is our wellness initiative something staff genuinely use, or something that exists mostly on paper?
- Do our people feel comfortable raising a mental health concern before it becomes a claim, or only after?
- Have we built wellness initiatives specific to the actual physical and mental demands of our roles, or adopted a generic package?
- Are we treating wellness as a one-off event, or as an ongoing part of how the business operates?
A wellness program won't replace good safety equipment or sound claims management but as part of a broader approach, it's one of the few investments that improves both staff experience and long-term insurance cost at the same time.