For many business owners, workers' compensation feels like a tax: a mandatory cost that shows up every year regardless of what happens on-site. In reality, it's one of the few insurance costs genuinely within your control. Premiums are calculated based on claims history and industry risk classification, which means the businesses that invest in safety consistently pay less over time than those that treat it as an afterthought.
Here's what actually moves the needle and what doesn't.
Understand How Your Premium Is Actually Calculated
Workers' compensation premiums are generally driven by three factors: your industry classification, your total wages, and your claims history (often called your "experience rating" or claims performance). Of these three, claims history is the one you can meaningfully influence. A business with a strong safety record and few or no claims will consistently be rated more favourably than one with a pattern of incidents, even within the same industry.
This means safety investment isn't just about doing the right thing by your staff it directly compounds into lower premiums year after year.
Where Most Workplace Injuries Actually Happen
Contrary to what many owners assume, the most common workplace injuries aren't dramatic accidents — they're the mundane, repeated risks that build up over time:
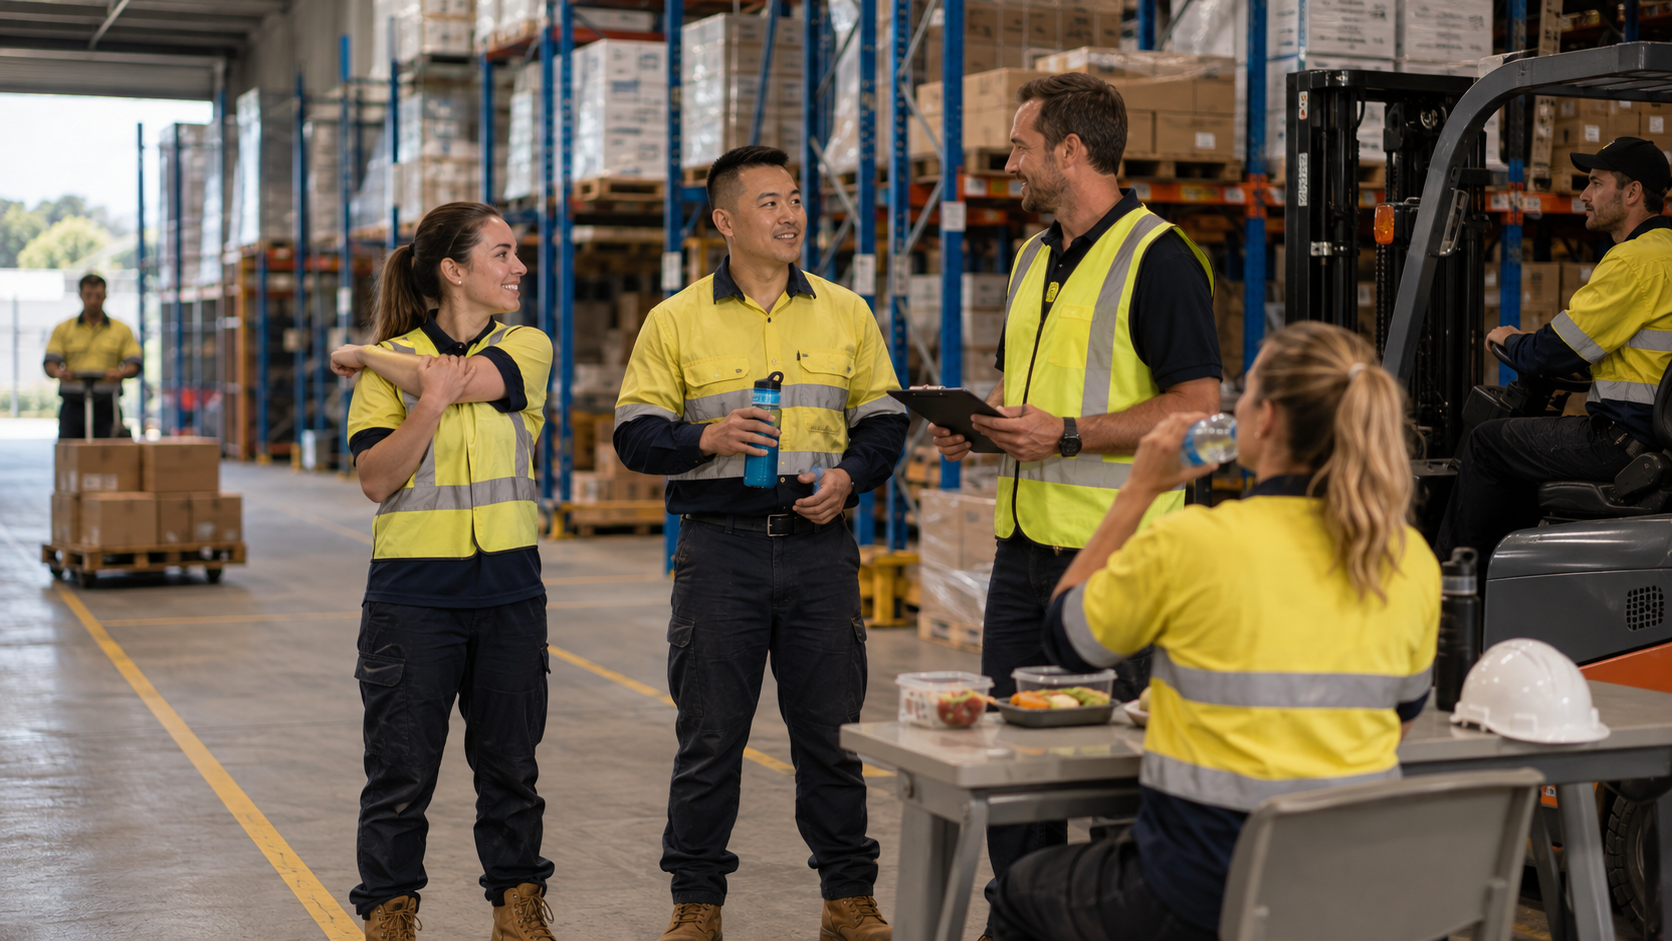
- Manual handling injuries from lifting, carrying, or repetitive motion
- Slips, trips, and falls from poor housekeeping or uneven surfaces
- Overexertion from working beyond safe physical limits, particularly under time pressure
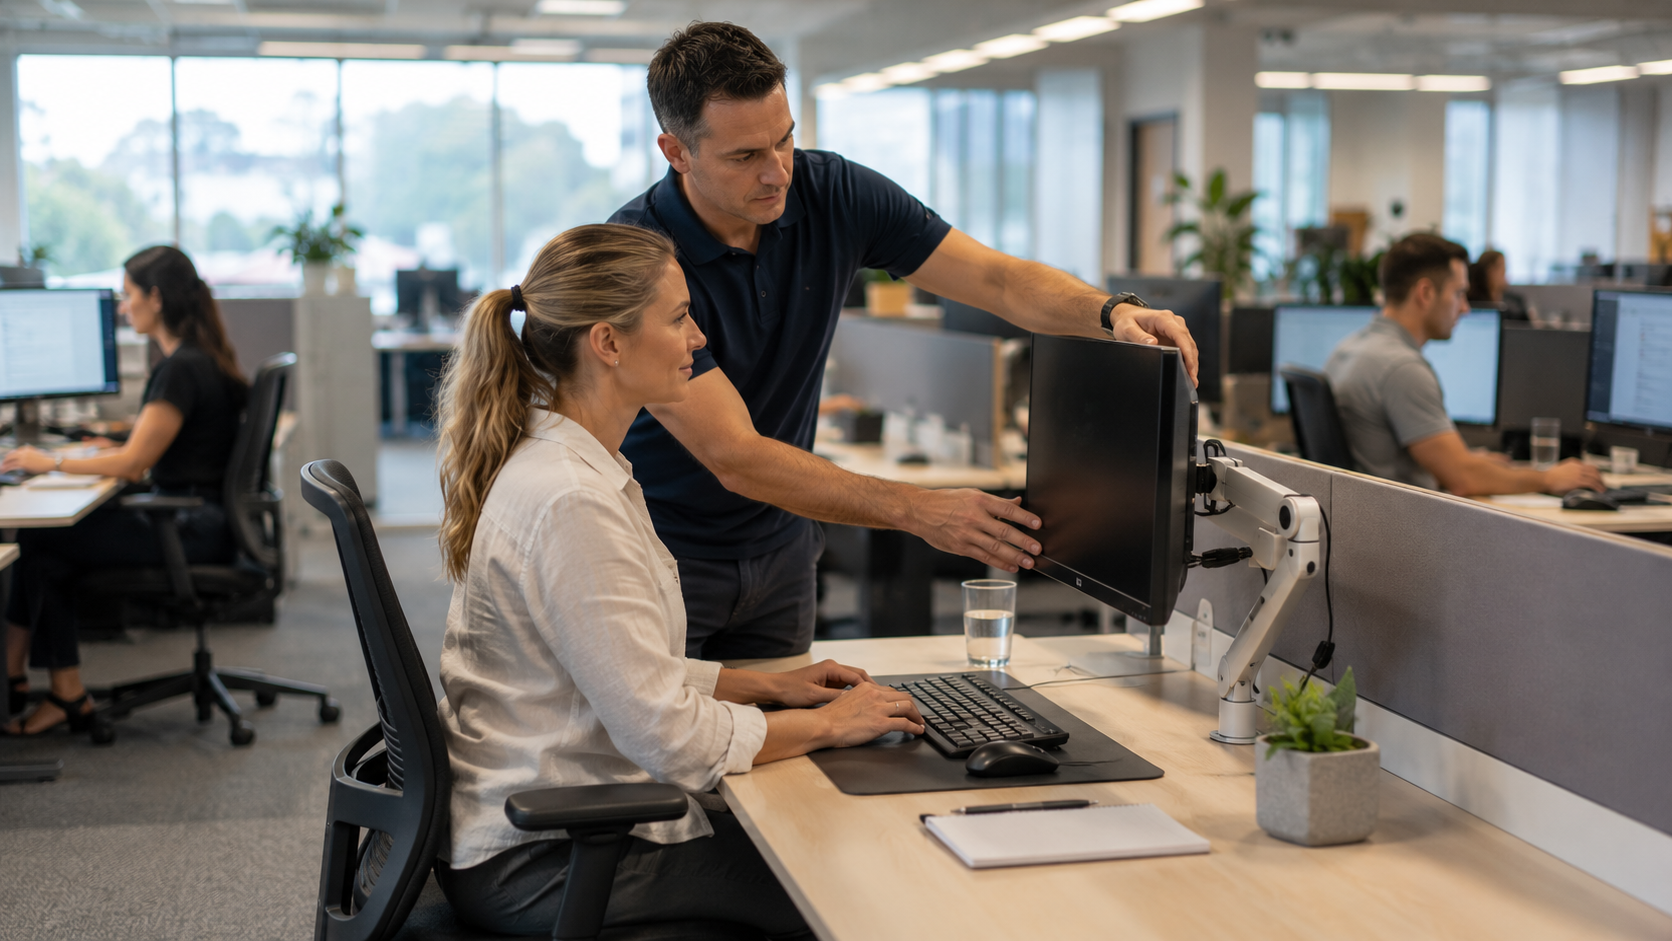
- Poor ergonomics in desk-based roles, leading to long-tail claims for musculoskeletal issues
None of these require dramatic new equipment to address they require consistent attention.
Five Practical Steps That Actually Reduce Claims
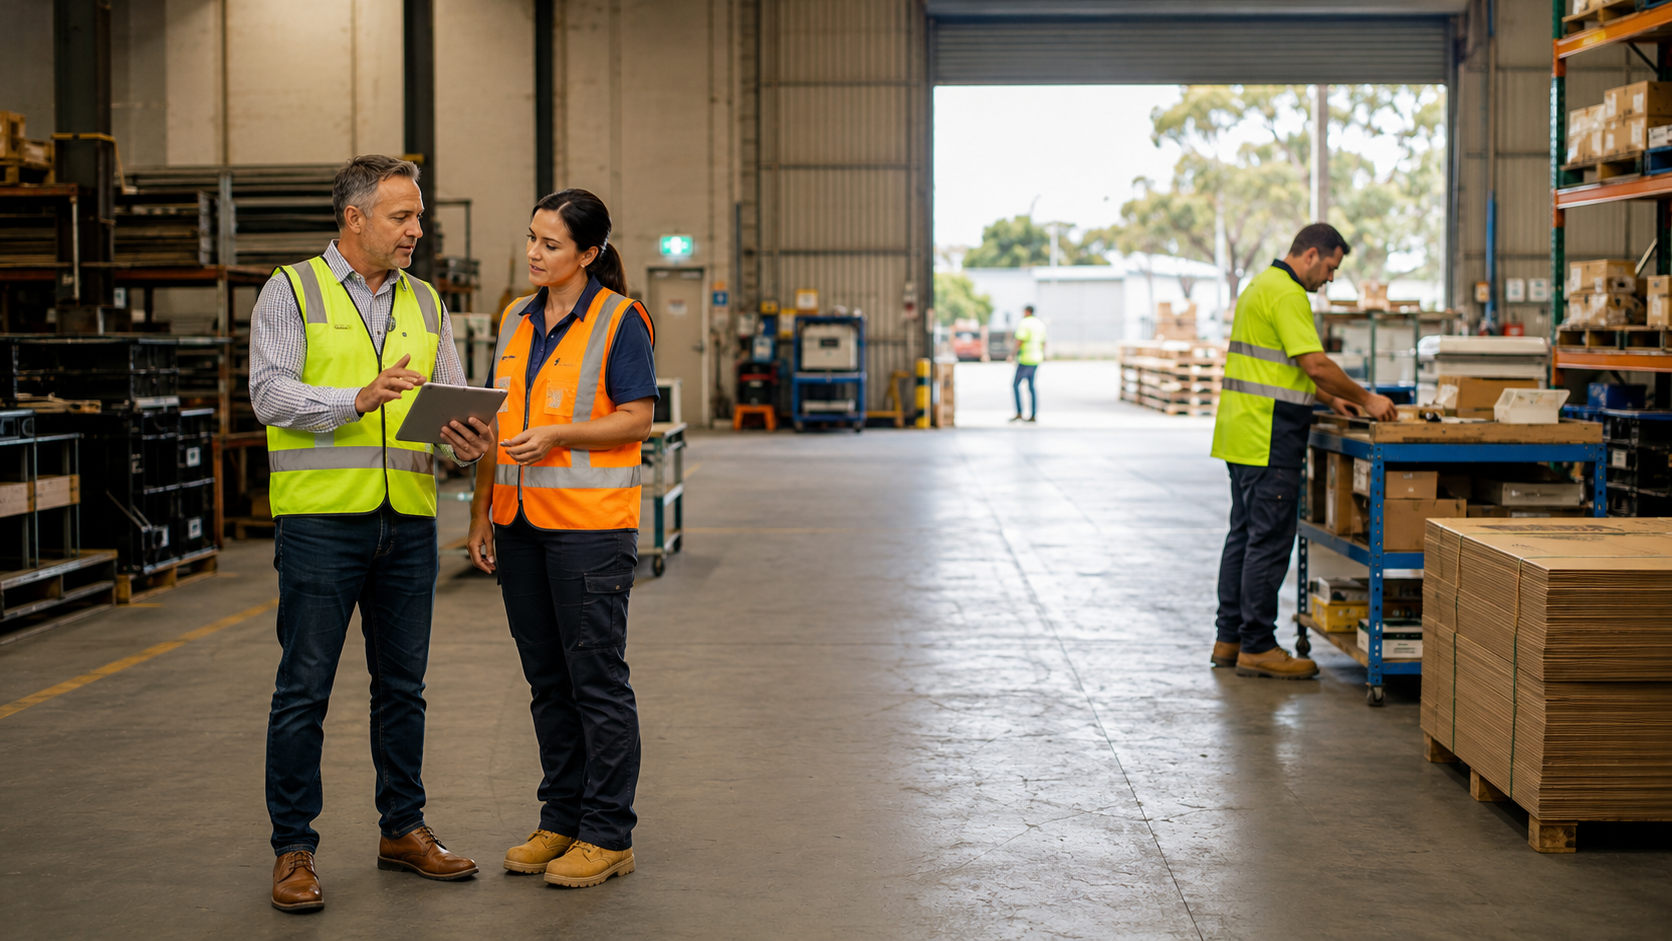
1. Conduct real (not paper-only) safety audits. A safety audit that exists purely to satisfy a compliance checklist won't change behaviour. Walk the floor, talk to staff doing the actual work, and look for the gap between what the procedure says and what people are actually doing under time pressure.
2. Fix near-misses, not just incidents. Most workplaces have a formal process for reporting injuries but a much weaker one for reporting near-misses the moments where something almost went wrong. Near-misses are free information about where your next claim is likely to come from.
3. Invest in manual handling training that's specific to your actual tasks. Generic manual handling training is better than nothing, but training built around your specific equipment, layout, and workflow prevents far more injuries than a one-size-fits-all module.
4. Support early and safe return to work. How an injury is managed after it happens has a significant impact on both the wellbeing of the employee and the ultimate cost of the claim. A structured, supportive return-to-work plan rather than an adversarial one tends to produce better outcomes for everyone, including your premium.
5. Make safety a leadership behaviour, not a poster on the wall. Workplaces where managers visibly follow safety procedures themselves see meaningfully better compliance than workplaces where safety is treated as something that applies to everyone except the people in charge.
The Compounding Effect
The businesses that benefit most from safety investment are rarely the ones looking for a single dramatic fix they're the ones that make small, consistent improvements over multiple years. Because claims history is assessed over a rolling period, the impact of a genuinely safer year doesn't just help this year's premium; it continues to help for several years afterward as your experience rating gradually improves.
This is why workplace safety is best thought of as a long-term investment strategy, not a compliance cost to be minimised.
A Word on Culture
Formal policies and training only go so far if the underlying culture doesn't support them. Workplaces where staff feel comfortable reporting hazards without fear of blame consistently outperform workplaces where incidents are quietly managed and forgotten. If your business has a culture where near-misses go unreported because staff don't want to be seen as the problem, that's often a bigger driver of long-term claims cost than any single physical hazard.
Talk to Your Broker Before Renewal, Not After a Claim
Many business owners only think carefully about their workers' compensation arrangement in the weeks before renewal or worse, after a significant claim. A broker who understands your industry can help you benchmark your claims history against similar businesses, identify where your premium is being driven by preventable factors, and connect you with practical resources for improving your safety record before it shows up as a cost.
Unsure how your safety record is affecting your premiums? Connect with a UIG Authorised Representative to review your workers' compensation arrangement.
A Realistic Example
Two businesses in the same industry, similar size, similar wages bill. One treats its annual safety audit as a compliance exercise a consultant walks through with a checklist once a year, ticks the boxes, and leaves. The other holds monthly toolbox talks, tracks near-misses seriously, and has a manager who visibly follows the same PPE rules as everyone else on the floor.
Three years later, the first business has had two moderate claims and sees its premium rated accordingly. The second has had none, and its experience rating reflects a business that's genuinely lower risk not because it got lucky, but because it built habits that actually reduce the odds of an incident in the first place. Same industry, same starting point, materially different outcome.
Questions Worth Asking About Your Own Workplace
- When did we last walk the floor and talk to the people doing the actual work, rather than reviewing a checklist?
- Are near-misses actually being reported, or are staff quietly managing them without telling anyone?
- Is our manual handling training generic, or built around what our people actually do day to day?
- Do our return-to-work plans support genuine recovery, or do they create friction that drags claims out longer than necessary?
- Would our managers pass their own safety audit, or are the rules seen as something that applies to everyone else?
A safety record isn't built in the weeks before renewal it's built in the eighteen months before that, in the habits nobody was watching closely at the time.